Life Insurance in Los Lunas, NM: A Plain-English Guide
A plain-language guide from an Albuquerque-based licensed agent who helps families across New Mexico.
✓ Free quote✓ No obligation✓ ⏱ 5-minute read
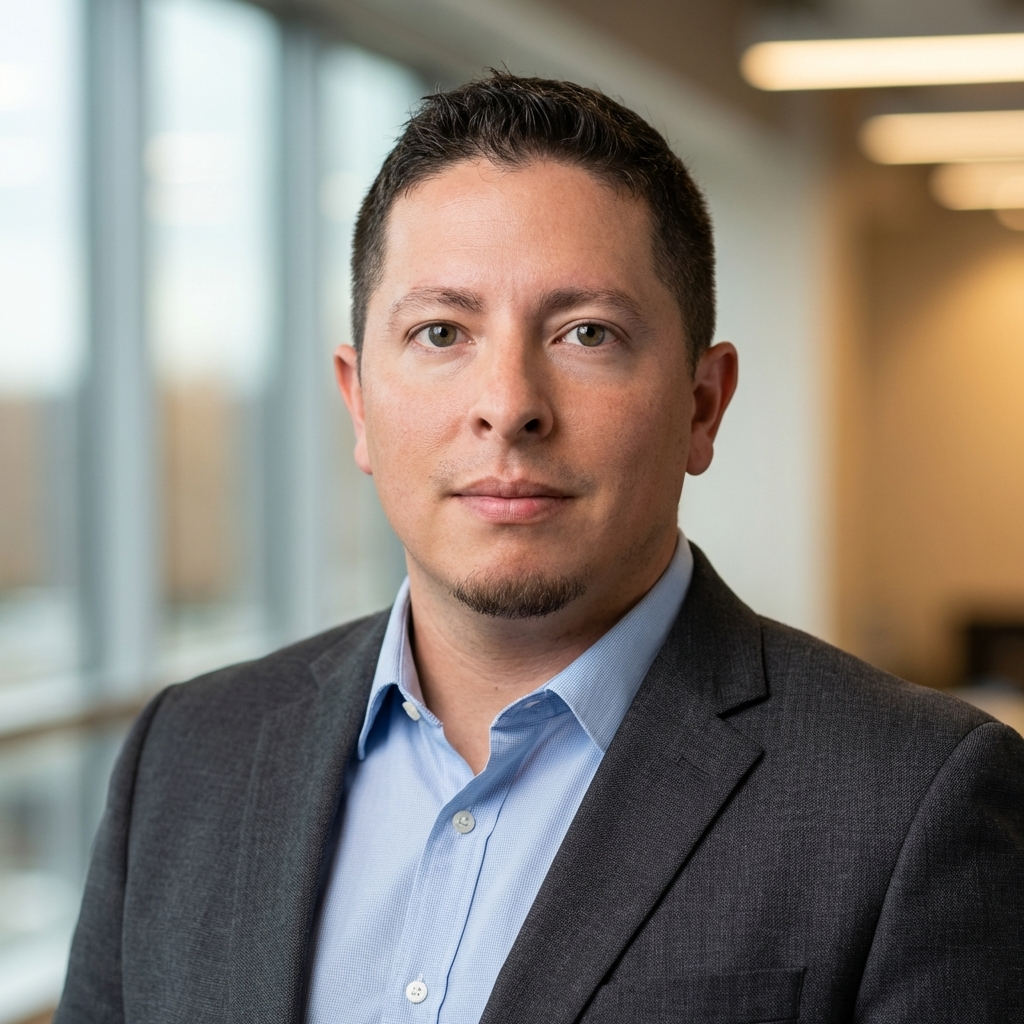
Paul Maldonado
Life Insurance Producer · Albuquerque, NM
NM License #20245906
✓ Helping families across all of New Mexico
If you live in Los Lunas or anywhere in Valencia County and you're thinking about life insurance, you probably want to understand how it works before anyone tries to sell you anything. This guide walks you through it in plain English — the myths, the main kinds of coverage, and how to figure out what makes sense for your family.
Myth vs. fact
Three things people get wrong
MYTH
“I'm young and healthy — I don't need it yet.”
FACT
Age and health are two of the biggest factors in price, so many people look at coverage while both are on their side.
MYTH
“My coverage through work is enough.”
FACT
Workplace coverage is often a set multiple of your salary and may end if you change jobs. Many families add personal coverage alongside it.
MYTH
“I have a health condition, so I can't get covered.”
FACT
Many insurance companies offer options for a range of health histories. Eligibility and price depend on each company's underwriting.
Meet the policies
Seven kinds of coverage, explained in plain English
Life insurance isn't one product. Each type below solves a different problem, and many families end up combining two.
Term life
Covers you for a set number of years — like 10, 20 or 30. It usually costs the least, which makes it popular while kids are young or a mortgage is being paid off. When the years are up, the coverage ends unless you renew or switch it to a permanent policy.
Whole life
Covers you for your entire life, as long as you keep paying. Your payment usually stays the same for life, and part of what you pay builds a savings value inside the policy that grows over time and that you can borrow against later.
Indexed universal life (IUL)
Covers you for life and builds savings, with payments you can adjust. Your savings can grow more in years the stock market does well — without your money actually being in the market. There's a limit on how much it can grow in a good year, and a floor so a bad market year adds zero instead of a loss. Policy costs still come out every year, so your savings can go down — it needs enough money kept in it to stay active.
Final expense
A smaller policy made to cover funeral and end-of-life costs, so your family isn't stuck with the bill. It usually has fewer health questions, which makes it easier to get later in life.
Mortgage protection
Life coverage matched to what you owe on your home. If you pass away, the money helps your family pay off the house or keep making payments, so they can stay in the home.
Living benefits
An add-on that lets you use part of your policy's money while you're still alive if you get seriously ill — like a heart attack, cancer or a terminal diagnosis. Whatever you use comes out of what your family receives later. Options vary by company.
Policies for children & grandchildren
Lifelong coverage on a child, bought while they're young and healthy, when it costs the least. Many let them buy more coverage as adults without answering health questions, and some build a small savings value along the way.
Not sure which one fits your family? That's exactly what the first call is for.
Your Los Lunas guide · 01
Why Los Lunas families start looking
Most people start thinking about coverage when someone depends on their paycheck — a new baby, a marriage, a first home, or a long daily drive up to Albuquerque for work.
The right coverage starts with one question: who would feel it if your paycheck stopped?
If your family would struggle to keep up with the house, the bills or future school costs without your income, that's a common reason to look at your options.
Your Los Lunas guide · 02
Figuring out how much coverage
There's no single right number. A simple way to start is to add up what your family would need, then subtract what you already have.
- Years of income your family would need to replace
- What's left on your mortgage or rent for the years ahead
- Car loans, credit cards and other debts
- School or college costs for your kids
- Funeral and final costs
- Minus savings and any coverage you already have through work
Your Los Lunas guide · 03
What to have ready before we talk
- A rough idea of your income and monthly bills
- Any life insurance you already have, including through work
- Who you'd want to receive the money
- A basic idea of your health history
Your Los Lunas guide · 04
Questions worth asking any agent
- How long does this coverage last, and what happens when it ends?
- Will my payment ever change?
- What happens if my family's needs change later?
- How would my family actually receive the money?
Your Los Lunas guide · 05
Before you buy
Life insurance is issued by insurance companies and is not a bank deposit or FDIC insured. Every policy is a contract, so read it carefully before you sign, and answer the application honestly — mistakes can affect whether a claim is paid.
In New Mexico, you can confirm that an agent or insurance company is licensed with the Office of Superintendent of Insurance.
If you'd like to talk it through, I'm happy to answer your questions — Los Lunas is just down the road.
From first question to policy in hand.
No pressure, no jargon. Here's what the process actually looks like.
Talk it through
Who you want to protect and what worries you.
Compare options
I shop several insurance companies and lay the choices side by side.
Apply
Health questions — sometimes a short exam. The company decides approval and price.
Policy in hand
Review it, sign it, name your beneficiaries.
Check in yearly
Life changes. We review your coverage every year.
Quick answers
How much coverage do people usually look at?+
A common starting point: add up the income your family would need to replace, your mortgage and debts, and future costs like college — then subtract savings and coverage you already have. I'm happy to walk through it with you.
Do I need a medical exam?+
Not always. Some policies use health questions and records only; others ask for a short exam. It depends on the insurance company, the amount and your age.
Can I have more than one policy?+
Yes. Many people combine policies — for example, term for the mortgage years plus a permanent policy for final expenses.
What happens if I stop paying?+
Term coverage ends. A permanent policy may use its savings value to keep coverage going for a while or offer a smaller paid-up policy — every contract spells this out.
Get yourself covered, so you and your family have peace of mind — while you enjoy your green chile and our beautiful New Mexico sunsets.
Anywhere in New Mexico? I can help.
A free conversation with no obligation. From Albuquerque to Las Cruces, Santa Fe to Farmington — I'll walk you through your options in plain language.